
Three or four years ago Comparison of the Bali and Dubai real estate markets It would have looked odd to compare it to Thailand – they were in completely different weight classes in terms of capital, brand recognition, and market size. Today, the picture is different: Dubai is going through a market correction with localized oversupply, Thailand remains hostage to seasonal tourist flows from a small group of countries, and Bali is gradually drawing capital from investors who previously looked exclusively to the UAE. For brokers working with international markets, this isn't an abstract trend, but a concrete reason to reconsider where exactly to direct client traffic in 2026. This material provides a digital basis for such a decision, compiled from market reports for 2026.
Where to direct capital: A comparative analysis of three investment hubs
ROI claims in marketing brochures rarely reflect reality: high returns on paper are easily offset by seasonal downtime or high entry barriers. To objectively assess the risks and capital growth horizons in each location, let's compare them across five basic metrics—from initial receipts to land price dynamics:
| Criterion | Bali | Dubai | Thailand (Phuket) |
| Entry threshold | from $100,000–150,000 (Leasehold) | from $150,000 (studio); Golden Visa – from $545,000 | from $120 000 (condominium) |
| Average net ROI | 9–12% | 4–6% (gross 6–8%) | 5–7% (gross 6–10%) |
| Seasonality | minimal, year-round demand | present in summer (May–September); compensated by long-term rental | High: November–March yields 55–65% of annual income |
| Rising land values | +15–30% for 2 years in top locations | uneven, localized oversupply (JVC, Arjan, Business Bay) | +4–8% per year |
| Average occupancy rate | 65% on average across the island, 70–85% in premium zones | 65–75% (high proportion of long-term residents) | 55–75%, with a seasonal dip to 40–50% |
The most telling line here isn't ROI, but seasonality in relation to occupancy. Dubai and Bali's low risk of downtime is ensured by two distinct mechanisms: a steadily growing population (Dubai) and a diversified tourist flow from dozens of countries (Bali). Thailand lacks such a buffer—its entire revenue plan hinges on the five-month peak season. This, not ROI itself, is the main argument for clients who compare stability, not just revenue figures. Below is a detailed breakdown of each market.
Dubai: High Entry Barriers and Sagging Net Returns
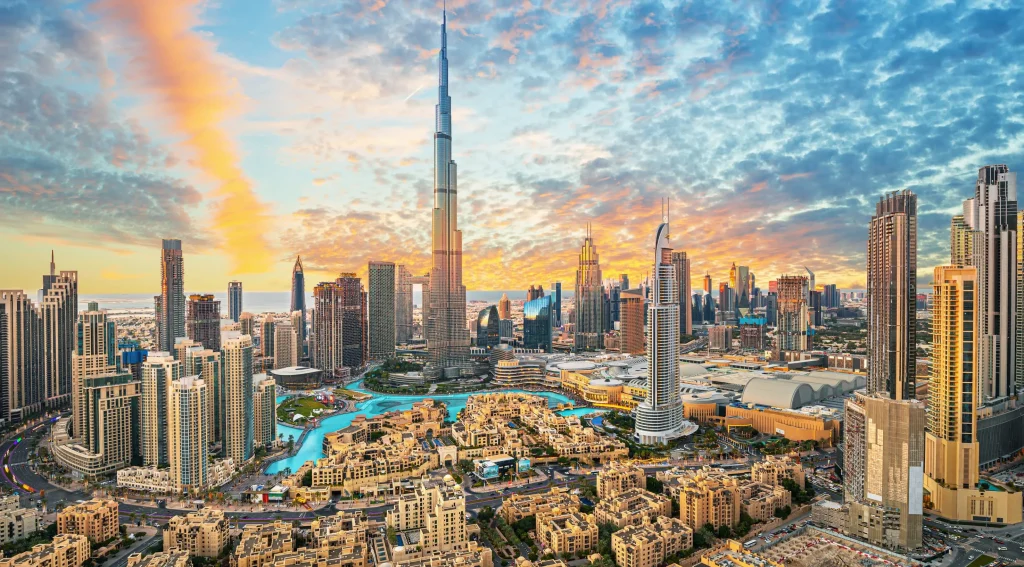
Dubai remains a clear, highly liquid market with zero property taxes and strong demand from the resident population. However, Bali real estate returns 2026 is already outperforming Dubai. Gross ROI in Dubai remains at 6–8%, but after subtracting service charges, downtime, and management costs, the net ROI drops to 4–6%.
The market is also going through a structural correction phase. In high-density areas (JVC, Arjan, Business Bay), more than 15,000 new units are scheduled for completion in 2026–2027, creating a localized oversupply and putting pressure on rental rates. The entry threshold has also increased: to obtain a Golden Visa, the investment must reach at least AED 2 million (~$1,545,000). Against this backdrop, the answer to clients' questions about, Where is the ROI higher: Bali or Dubai?, it becomes obvious in favor of the Indonesian island.
Thailand (Phuket): Strong seasonality and tight quotas
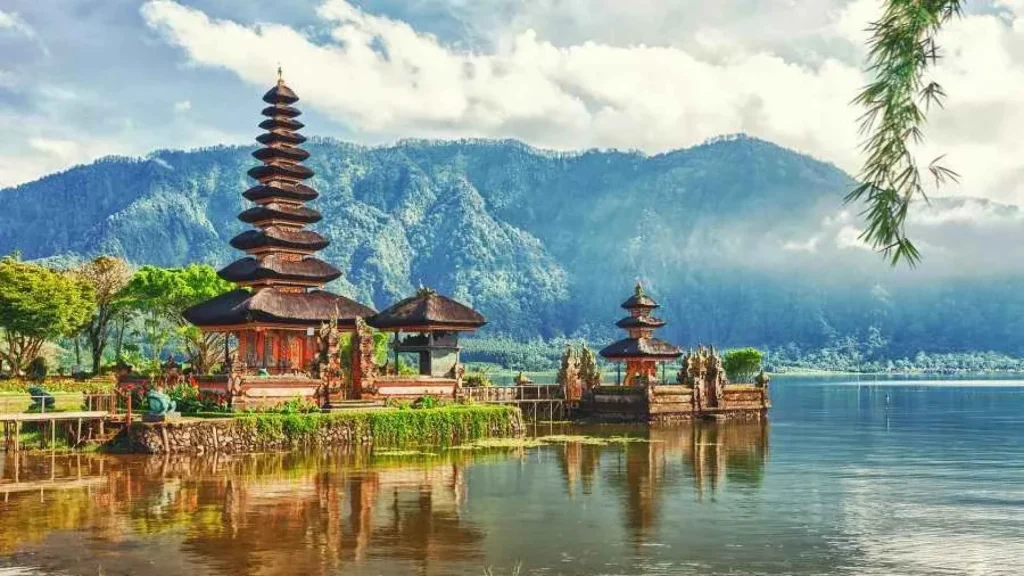
Market analysis shows that for clients considering Thailand, the key risk is not so much the entry threshold as the stability of cash flow. Gross ROI in Phuket can reach 6–10% in prime locations (Bang Tao, Rawai), but net ROI typically ranges from 5–7%.
The main reason is the strict seasonality: the period from November to March generates up to 60% of annual property revenue, while during the low season (May–October), occupancy drops to 40–50%. Developers often declare 80–90% of annual occupancy in their brochures, but actual data from rental operators shows an average annual result of 55–75%.
An additional risk factor is the legal status and narrow tourist base. Foreign buyers are limited to a 49% freehold quota for condominiums, and purchasing villas requires complex 30-year leasehold arrangements.
Why Bali Is Dragging Capital: Comparative Economics
Comparing investments Thailand or Bali, An investor chooses between seasonal income and a market with virtually year-round high occupancy. Bali diversifies risks through global tourism, making it resilient to local economic or geopolitical shocks.
The island's main growth driver is a fundamental land shortage. While new construction phases in Dubai curb price growth, in Bali, the limited land supply in scarce locations (such as Uluwatu) directly contributes to the capitalization of properties.
Comparison summary:
- Net ROI: 9–12% (up to 14% in top properties) – higher than Dubai and Phuket;
- Entry threshold: from $100,000–150,000, which is more affordable than the institutional threshold in the UAE;
- Seasonality: the absence of pronounced «dead months» guarantees a stable cash flow;
- Capital growth: Land shortage ensures an increase in the value of properties by +15–30% over 2 years in hot locations.
Comparing the Bali and Dubai Real Estate Markets, as well as a comparison with Thailand, shows that overheated markets haven't completely lost their appeal, but their net yields are systematically shrinking due to oversupply in the UAE and seasonality in Thailand. In 2026, Bali remains a market where land scarcity and year-round demand favor investors.
Use analytics and digital financial models ANTA Group, To address any concerns your buyers may have and redirect their capital to the most profitable locations. Request a brokerage package with current properties and ROI calculations now.